
Global In Vitro Diagnostics (IVD) Market Insights, Growth, Share, Size: By Offering, By Application, By Clinical Indication, By End Users, By Sales Channel, By Region & Segmental Forecast, 2023-2031, Comparative Analysis and Trends
- Industry: Healthcare
- Report ID: TNR-110-1052
- Number of Pages: 420
- Table/Charts : Yes
- January, 2024
- Base Year : 2024
- No. of Companies : 10+
- No. of Countries : 29
- Views : 10087
- Covid Impact Covered: Yes
- War Impact Covered: Yes
- Formats : PDF, Excel, PPT
Global In Vitro Diagnostics (IVD) Market was Valued at USD 117.8 Bn in 2022, Growing at an Estimated CAGR of 4% During 2023 – 2031.
In Vitro Diagnostics (IVD) refers to tests and procedures performed on biological samples (such as blood, urine, tissue) taken from the human body. These tests are conducted outside the body, usually in a laboratory setting, to diagnose diseases, monitor health conditions, and guide treatment decisions. IVD has significantly evolved over time, and its use has become integral to modern healthcare.
The emergence and evolution of in vitro diagnostics (IVD) market has been shaped by centuries of scientific inquiry, technological advancements, and the quest to understand and combat diseases. IVD has become an indispensable part of modern healthcare, aiding in disease diagnosis, monitoring, and personalized treatment approaches.
Global In Vitro Diagnostics (IVD) Market Revenue & Forecast, (US$ Million), 2015 – 2031
The growth of the global in vitro diagnostics (IVD) market has been driven by several key factors. Technological advancements play a crucial role, with companies like Roche Diagnostics innovating automated molecular testing systems such as the cobas platforms, elevating the accuracy and efficiency of diagnostics. The prevalence of chronic diseases like diabetes, cancer, and cardiovascular conditions has fueled the demand for diagnostic tests, prompting companies such as Abbott Laboratories and Siemens Healthineers to develop various tests and platforms tailored to these ailments. Moreover, aging population has led to an increased need for diagnostics targeting age-related diseases, prompting companies like BD and bioMérieux to introduce specialized tests and systems catering to geriatric healthcare needs.
The demand for point-of-care testing (POCT) has surged, prompting companies like Abbott and Quidel to create portable and rapid testing devices that provide immediate results, aligning with the need for quick diagnoses. The COVID-19 pandemic acted as a catalyst, accelerating innovation and demand for diagnostic tests. Companies including Thermo Fisher Scientific, Roche, Abbott, and Qiagen played significant roles in developing and scaling up COVID-19 tests, including PCR and rapid antigen tests, showcasing the industry’s agility and responsiveness in crisis situations.
Advancements in genomics and personalized medicine have led to the development of companion diagnostics, where companies like Foundation Medicine (a Roche company) have crafted tests to identify genetic mutations for targeted cancer therapies. Emerging markets with increasing healthcare expenditure and improving infrastructure have become focal points for growth, prompting companies such as Sysmex Corporation and Ortho Clinical Diagnostics to expand their presence in these regions. Lastly, regulatory changes emphasizing quality standards have pushed companies to invest in research and development, ensuring compliance and obtaining necessary approvals for their diagnostic products. This collective innovation across companies continues to shape and enhance the landscape of diagnostic technologies, addressing evolving healthcare needs on a global scale.
 Offerings OutlookSemiautomated systems have significantly contributed for largest market share within the system & instruments category of the in vitro diagnostics (IVD) market. These systems blend human intervention with automated processes, offering a balance between manual and fully automated systems. Their popularity arises from their ability to streamline workflows while retaining some level of user control and flexibility.
In various segments of diagnostics such as clinical chemistry, hematology, and coagulation testing, semiautomated systems have been pivotal. They allow for efficient sample processing, reducing human error while enabling laboratory professionals to oversee and verify results. Companies like Sysmex, Beckman Coulter, and Siemens Healthineers have developed semiautomated systems that provide accuracy, reproducibility, and faster turnaround times. These systems appeal to laboratories of different sizes – from smaller facilities that need some automation to larger labs seeking to complement their fully automated lines. Their adaptability and cost-effectiveness make them a preferred choice for many diagnostic settings. As the industry progresses with a focus on enhancing efficiency and accuracy, semiautomated systems continue to hold a substantial market share in the global in vitro diagnostics (IVD) market due to their ability to strike a balance between manual dexterity and automation in the diagnostic process.
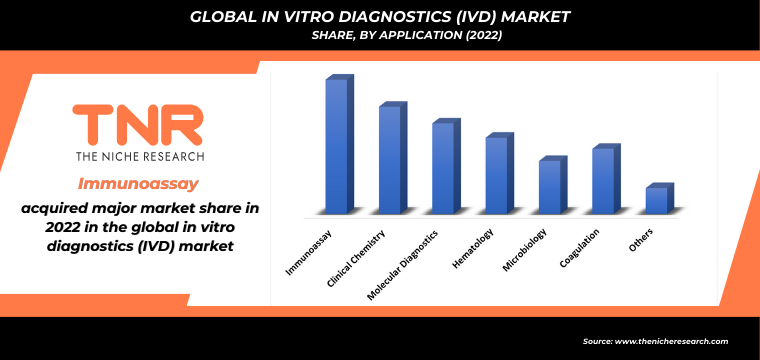 Application OutlookThe dominance of the immunoassay segment in the in vitro diagnostics (IVD) market in 2022 highlights the significance of this diagnostic technique. Immunoassays are crucial in detecting and quantifying specific molecules like hormones, proteins, and antibodies present in biological samples. Their wide application across various medical fields, including infectious diseases, oncology, endocrinology, and autoimmune disorders, contributes to their market dominance. Several factors have propelled the immunoassay segment to the forefront of the vitro diagnostics (IVD) market. The increasing prevalence of chronic and infectious diseases worldwide has led to a growing demand for precise and sensitive diagnostic tools, which immunoassays excel at providing. Companies like Roche Diagnostics, Abbott Laboratories, and Siemens Healthineers have developed advanced immunoassay platforms offering high sensitivity, specificity, and automation, further driving the segment’s dominance.
Clinical Indication Outlook
The infectious diseases segment’s large market share in the in vitro diagnostics (IVD) market is driven by the pressing need for accurate and rapid diagnostic solutions in identifying and managing infectious conditions like HIV, hepatitis, tuberculosis, and emerging pathogens like the SARS-CoV-2 virus responsible for COVID-19. Companies have developed innovative molecular diagnostics, immunoassays, and rapid antigen tests, driving the segment’s prominence.
Regional Outlook North America has historically held a dominant position in the global in vitro diagnostics (IVD) market. The region’s prominence is fueled by various factors, including advanced technological capabilities, substantial healthcare investments, and a competitive landscape of leading companies. The United States and Canada, in particular, have been pivotal in driving innovation and the adoption of sophisticated diagnostic tools. Companies like Abbott Laboratories, Thermo Fisher Scientific, and Roche Diagnostics have established themselves as key players, continuously developing cutting-edge IVD technologies.

Moreover, North America’s significant healthcare spending contributes to the widespread utilization of advanced diagnostics across hospitals, clinics, and research institutions. This financial commitment allows for the incorporation of state-of-the-art IVD solutions into the healthcare system, fostering early disease detection, precision medicine, and improved patient care.
The region’s competitive market environment encourages continuous advancements and the introduction of novel diagnostic solutions, sustaining its leadership in the global in vitro diagnostics (IVD) market landscape. This dominance is expected to persist as North America remains a hub for technological innovation, strategic investments, and a strong emphasis on healthcare excellence.
Competitive Landscape: Global In Vitro Diagnostics (IVD) Market
- Abbott Laboratories
- BD
- bioMérieux SA
- Bio-Rad Laboratories, Inc.
- Danaher Corporation
- DiaSorin S.p.A.
- Hoffmann-La Roche Ltd
- Ortho Clinical Diagnostics.
- QIAGEN
- Siemens Healthineers
- STRATEC SE (Diatron MI Zrt)
- Sysmex Europe GmbH.
- Thermo Fisher Scientific
- Other Industry Participants
Global In Vitro Diagnostics (IVD) Market Summary
| Report Specifications | Details |
| Market Revenue in 2022 | US$ 117.8 Bn |
| Market Size Forecast by 2031 | US$ 217.9 Bn |
| Growth Rate (CAGR) | 4% |
| Historic Data | 2015 – 2021 |
| Base Year for Estimation | 2022 |
| Forecast Period | 2023 – 2031 |
| Report Inclusions | Market Size & Estimates, Market Dynamics, Competitive Scenario, Trends, Growth Factors, Market Determinants, Key Investment Segmentation, Product/Service/Solutions Benchmarking |
| Segments Covered | By Offering, By Application, By Clinical Indication, By End Users, By Sales Channel |
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
| Countries Covered | U.S., Canada, Mexico, Rest of North America, France, The UK, Spain, Germany, Italy, Nordic Countries (Denmark, Finland, Iceland, Sweden, Norway), Benelux Union (Belgium, The Netherlands, Luxembourg), Rest of Europe, China, Japan, India, New Zealand, Australia, South Korea, Southeast Asia (Indonesia, Thailand, Malaysia, Singapore, Rest of Southeast Asia), Rest of Asia Pacific, Saudi Arabia, UAE, Egypt, Kuwait, South Africa, Rest of Middle East & Africa, Brazil, Argentina, Rest of Latin America |
| Key Players | Abbott Laboratories, BD, bioMérieux SA, Bio-Rad Laboratories, Inc., Danaher., DiaSorin S.p.A., F. Hoffmann-La Roche Ltd, Ortho Clinical Diagnostics., QIAGEN, STRATEC SE (Diatron MI Zrt), Siemens Healthineers, Sysmex Europe GmbH., Thermo Fisher Scientific, Other Market Participants |
| Customization Scope | Customization allows for the inclusion/modification of content pertaining to geographical regions, countries, and specific market segments. |
| Pricing & Procurement Options | Explore purchase options tailored to your specific research requirements |
| Contact Details | Consult With Our Expert
Japan (Toll-Free): +81 663-386-8111 South Korea (Toll-Free): +82-808- 703-126 Saudi Arabia (Toll-Free): +966 800-850-1643 United Kingdom: +44 753-710-5080 United States: +1 302-232-5106 E-mail: [email protected]
|
Global In Vitro Diagnostics (IVD) Market ScopeBy Offering
- Products
- Systems & Instruments
- Fully Automated Systems
- Semi-Automated Systems
- Others
- Assays and Reagents
- Calibrators & Control Materials
- Reagent Kits
- Others
- Systems & Instruments
- Software
- Information/Data Management Software
- Lab Automation Software
- Others
- Services
By Application
- Immunoassay
- Clinical Chemistry
- Molecular Diagnostics
- Hematology
- Microbiology
- Coagulation
- Others
By Clinical Indication
- Infectious Disease
- Hepatitis
- Coronavirus Disease (COVID-19)
- Others
- Oncology
- Diabetes
- Cardiology
- Gynecology and Women’s Health
- Bone Health
- Autoimmune Diseases
- Others
By End Users
- Hospitals
- Emergency Care Centers
- Clinical Diagnostics Laboratories
- Academic & Research Institutions
- Home Care
- Others
By Sales Channel
- Direct
- Indirect
By Region
- North America (U.S., Canada, Mexico, Rest of North America)
- Europe (France, The UK, Spain, Germany, Italy, Nordic Countries (Denmark, Finland, Iceland, Sweden, Norway), Benelux Union (Belgium, The Netherlands, Luxembourg), Rest of Europe)
- Asia Pacific (China, Japan, India, New Zealand, Australia, South Korea, Southeast Asia (Indonesia, Thailand, Malaysia, Singapore, Rest of Southeast Asia), Rest of Asia Pacific)
- Middle East & Africa (Saudi Arabia, UAE, Egypt, Kuwait, South Africa, Rest of Middle East & Africa)
- Latin America (Brazil, Argentina, Rest of Latin America)
Report Coverage & Deliverables
Table of Contents